What non-rent revenue does to your exit cap

Ancillary revenue conversations in multifamily usually stop at the operating statement. The program produces income, the income lands in other income, other income rolls into net operating income, and the discussion moves on.

The part that gets skipped is the one that matters most to an owner. At disposition, an underwriter decides how much of that other income is real. Some of it is accepted into the underwritten figure. Some of it is discarded. The tests are published, they are specific, and most operators have never read them.

This article is about those tests. It does not estimate what any portfolio’s non-rent revenue is worth, because that number depends on your own audited figures and your own market. What it does is explain what determines whether the number counts at all.

Why this question got more important

The rent side has been doing very little of the work.

Yardi Matrix reported that the average United States advertised rent “rose $4 to $1,771” in its most recent monthly release, describing “a 1.3% year-to-date increase in advertised rates over the past five months” and “year-over-year rent growth remaining weak amid a record number of apartment deliveries.” RealPage Analytics characterized the longer arc as “rent growth running below 1% year-over-year for nearly 30 months,” alongside average concessions reaching “the equivalent of 36 days of free rent.”

The expense side has not been as accommodating. The National Apartment Association reported that “average annual rent reached $21,502 per unit in 2024, rising just 1.2% from 2023, following growth of 2.9% in 2023 and 11.4% in 2022,” and that “since 2021, repairs and maintenance costs have risen nearly 28%, while Net Operating Income (NOI) has increased just 10% during the same period.”

When rent growth is flat and expenses are not, the composition of net operating income becomes a live question rather than an accounting detail.

How value is actually set

The mechanism is simple and worth stating precisely, because the precision is where the operational requirements come from.

CBRE defines it directly in its cap rate survey work: “stabilized cap rates are the ratio of stabilized net operating income (NOI) to the acquisition price of the asset.” The Freddie Mac Multifamily Seller/Servicer Guide sets out the same approach in its valuation chapter, noting that “the Property’s value can be developed with either a multiplier analysis or direct capitalization analysis,” and that the “capitalization Rate must be based on factors reflecting the investment characteristics of knowledgeable investors for properties similar to the Property.”

So value follows underwritten net operating income. Which means the operational question is narrow and answerable: how much of your non-rent revenue survives into the underwritten figure.

On where cap rates currently sit, CBRE reported core multifamily going-in cap rates at 4.75% and exit cap rates at 4.95% in its Q4 2025 survey, with value-add going-in at 5.26% and value-add exit at 5.38%. Note that the exit cap is published separately from the going-in cap, which is the whole point of this discussion. The exit assumption is where a buyer’s view of durable income shows up.

What the agencies actually require

Both agencies publish their treatment of other income, and the language is unusually clear.

The Freddie Mac Multifamily Seller/Servicer Guide, at Section 60.17(e), states that “the appraiser may include income from sources other than residential units when calculating total gross income if such income is supported by at least three years’ historical operations, is common in the market and is expected to continue in the future.” The Guide lists examples including “commercial space, laundry, parking, cable television, vending and application fees.”

The Fannie Mae Multifamily Selling and Servicing Guide, at Section 203.01, applies comparable tests to underwritten net cash flow. Other income must “be stable” and “be supported by prior years,” and the underwriter must “exclude one-time extraordinary non-recurring items.” The Guide requires an assessment of “the individual month’s other income within the prior full-year operating statement or, at a minimum, an operating statement covering at least the trailing 6 months (annualized),” and constrains how fluctuating income can be used: “if there are fluctuations, you may use other income that exceeds the trailing 3-month other income (annualized), provided it does not exceed the highest 1-month other income used in the trailing 3-month other income calculation.”

Read together, four tests emerge. The income has to recur. It has to be documented across periods. It has to be normal for the market. And anything one-time gets stripped out.

Translating the tests into operations

Those four tests are underwriting language. Each has an operational equivalent that an operations team can act on.

Recurrence means the revenue has to be produced by a process rather than by an effort. If the income exists because a particular regional manager runs a good program, it will show gaps the moment that person changes roles, and gaps show up as fluctuation in exactly the trailing-period tests the agencies apply.

Documentation means the transactions have to live in a system of record, attributable to a property and a period. Revenue reconstructed from vendor statements at diligence is revenue an underwriter will discount, because it cannot be tied to the property’s own books cleanly.

Market normalcy means the services should be ones a buyer recognizes. Movers, packing, storage, insurance, utilities and connectivity are services residents in residential real estate buy during every move. Their presence in other income reads as ordinary rather than as an aggressive assumption.

Excluding one-time items means promotional pushes and one-off campaigns should be understood for what they are. They may be good business. They will not carry into an underwritten figure, and treating them as if they will produces a valuation conversation that goes badly.

Where most programs fail

Four patterns account for most of the gap between reported non-rent revenue and underwritten non-rent revenue.

The revenue sits in a single undifferentiated other income line. When a buyer asks what is inside it, the answer takes weeks to assemble and arrives incomplete. A category nobody can decompose is a category a buyer discounts.

The program varies across the portfolio. Different offer sets by region produce a consolidated number that fluctuates for reasons unrelated to demand, and fluctuation is precisely what the agency trailing-period tests penalize.

Attribution is missing. Vendor-side reporting shows totals. Property-level, period-level attribution is what an underwriter needs, and it has to come from the operator’s own records.

And the revenue depends on human memory at the point of the move. Any process that requires a leasing associate to remember an offer during a busy move-in and move-out period will produce inconsistent results, which reads as instability in the numbers regardless of the underlying demand.

Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services and insurance verification directly into the workflow.

The reporting standard worth holding

An operator who wants non-rent revenue to count at disposition should be able to produce, on request, four things.

A breakdown of other income by service category rather than a single line. Monthly figures across a multi-year history, matching the periods the agencies test. Property-level attribution for every dollar. And a written description of the process that generates the revenue, showing it does not depend on any individual.

That package is what turns a program into an underwritable income stream. Without it, the revenue is real in the operating statement and absent from the valuation.

Frequently asked questions

Does other income really affect valuation, or does the buyer just look at rent?

Both agencies explicitly permit other income in the underwritten figure when it meets their tests, and CBRE’s definition ties value directly to net operating income. The constraint is on quality of evidence rather than on the category itself.

How many years of history do we need?

Freddie Mac’s appraisal guidance references “at least three years’ historical operations” for other income sources. Fannie Mae’s underwriting tests work off the prior full year or, at minimum, a trailing 6-month operating statement annualized, with additional constraints on fluctuating income. Building the record early is the practical takeaway.

We are not selling for years. Does this matter now?

The history requirement is the reason it matters now. A three-year record cannot be created retroactively at the point of sale. The operators who benefit are the ones who instrumented the revenue several years before anyone opened a data room.

What is the single highest-value change to make first?

Move the revenue into a system of record with property-level and category-level attribution. Every other test becomes answerable once the data exists, and none of them are answerable until it does.

Closing

Non-rent revenue reaches valuation through net operating income, and only the portion an underwriter accepts makes the trip. The tests are published by both agencies and they reward the same things: recurrence, documentation, market normalcy, and the absence of one-time items. Those are operational properties. They are built into how the revenue is generated and recorded, years before the exit cap is ever negotiated.

If you manage 10,000 units or more and want to review whether your non-rent revenue would survive an underwriter’s tests, reach out to our team.

Related reading: how the move-in and move-out workflow produces revenue for property managers, and the complete guide to resident onboarding automation. See also Moved for multifamily operators and the resident experience.

Why free move-in platforms are not free

Every operator evaluating move-in technology eventually meets a product that costs nothing. No licence fee, no per-unit charge, no implementation invoice. For an operations team under budget pressure, that is a compelling opening.

It is also incomplete. Software has a cost structure whether or not the operator sees an invoice. In a model where the operator pays nothing, the revenue is coming from the resident, either through what the resident buys or through access to the resident. That is a legitimate way to build a business. It is also a set of decisions the operator is making on the resident’s behalf, usually without examining them.

Three questions surface what is actually being agreed to.

Question one: who is paying, and for what

Ask the vendor to describe the full revenue model in plain language. Which counterparties pay them, for what, and on what basis.

There is a real distinction between two models that can look identical in a demo. In the first, the vendor earns from services the resident genuinely needs and would otherwise buy elsewhere. Movers, packing, storage, and insurance fall into this category. The resident wanted the service, the vendor delivered it, and the economics follow the delivery.

In the second, the vendor earns from access to the resident. The product is the resident’s attention or the resident’s data, sold to third parties who want to reach a household at a moment of high purchasing intent. The move-in workflow becomes a distribution channel.

Both models can be run well. They carry different risks for the operator, and only one of them keeps the operator’s interests and the resident’s interests pointing the same direction.

The FCC has already ruled on one version of this

This is not an abstract concern. Regulators examined a specific form of it in residential real estate and prohibited it.

In its 2022 order on competitive broadband access to multiple tenant environments, the Federal Communications Commission stated: “We prohibit a provider from entering into or enforcing an exclusive revenue sharing agreement with an MTE owner.” The Commission found such agreements “anti-competitive” and said they “amount to de facto exclusive access agreements.”

The order went further and addressed graduated arrangements as well: “We also prohibit providers from entering into or enforcing graduated revenue sharing agreements with MTE owners.” Under those arrangements, “a provider pays an MTE owner a greater percentage of revenue as its penetration in the building increases,” which the Commission found “discourage competitive entry to MTEs.”

The reasoning is worth holding onto beyond broadband. When a vendor’s payment to the owner rises with how many residents the vendor captures, the owner acquires a financial interest in limiting the resident’s alternatives. That structure attracts regulatory attention wherever it appears.

Question two: what happens to the resident’s data

A move-in platform sees a household at its most exposed. Names, forwarding addresses, move dates, service selections, sometimes payment details and identity documents. Ask three specific things.

Who owns that data contractually. Where it can be sent. And what happens to it when the agreement ends.

The regulatory floor here is not theoretical for large operators. Under the California Consumer Privacy Act, as the California Apartment Association set out for its members, a business is covered if it has “gross annual revenues in excess of $25 million,” or “buys, receives, or sells the personal information of 50,000 or more consumers, households, or devices,” or “derives 50 percent or more of annual revenues from selling consumers’ personal information.” Residents covered by the law have the right to “opt-out of sale of personal information,” and a right “to non-discrimination in terms of price or service when a consumer exercises a privacy right under CCPA.”

The National Multifamily Housing Council flagged the same territory for the industry, publishing guidance that “identifies 14 specific steps firms should take to prepare for existing and forthcoming legislation” and advising that firms “can prepare by proactively accounting for data privacy and security considerations in business operations.”

Most operators sign move-in vendor agreements without answering the three questions above. The exposure sits with the operator regardless, because the resident handed over the information believing they were dealing with their apartment community.

Question three: whose name is on it when something goes wrong

A mover damages furniture. A service the resident selected inside your portal never shows up. An insurance policy the resident believed was in place turns out not to be.

The resident does not call the vendor. They call the leasing office, because the offer appeared inside your workflow, under your brand, at your community. Whatever the contract says about liability, the reputational cost lands on the operator.

This is where free becomes expensive in a way that never appears in the software budget. The operator has outsourced the resident experience to a party whose commercial incentive is transaction volume, while retaining the reputational consequences of how those transactions go.

Resident-facing surveys suggest operators already misjudge what residents notice. Reporting Zego’s 2025 Resident Experience Management Report, NAA found that “apartment operators ranked a technology-enabled lifestyle as being the most important to renters. Renters disagree and rank this as a much lower priority.” The same research found that according to renters, the top three reasons they are not going to renew are “rent is too expensive; poor maintenance response; security issues,” and concluded that “many properties are losing good residents for preventable reasons.”

The gap between what operators believe residents value and what residents report valuing is the gap a poorly governed vendor relationship widens.

The regulatory floor is rising

Disclosure standards in rental housing are tightening, which raises the cost of an unexamined arrangement.

In March 2026 the Federal Trade Commission opened an advance notice of proposed rulemaking on rental housing fee practices. Christopher Mufarrige, Director of the FTC’s Bureau of Consumer Protection, stated that “rental pricing practices that are neither clear nor transparent undermine competition and harm consumers.” The Commission noted that “the failure to advertise the true total rent limits consumers’ ability to make informed financial decisions, increasing their search costs.”

Enforcement preceded the rulemaking. The FTC noted that Invitation Homes agreed to pay $48 million over allegedly “excluding mandatory monthly fees from the advertised rent,” and that Greystar Real Estate Partners was ordered to pay $23 million for allegedly having “misrepresented the true cost of renting a property and excluded mandatory fees from the advertised rent.”

None of that speaks directly to move-in platforms. It establishes the direction of travel. An operator who can explain exactly what every party earns, and can show that residents were told plainly, is in a materially better position than one who cannot.

What a defensible arrangement looks like

A few characteristics distinguish a vendor relationship an operator can stand behind.

The revenue model is disclosed in full and the operator can restate it from memory. If explaining how the vendor makes money requires the vendor in the room, the operator does not understand what they have signed.

The monetized services are services the resident actually needs. Movers, packing, storage, and insurance are purchases the household is making regardless. Insurance in particular belongs in the workflow as financial risk mitigation, verified before keys change hands rather than chased afterwards.

Resident choice is real. The resident can decline any service and still complete their move-in and move-out without friction or penalty.

Data ownership sits with the operator, with defined limits on where information travels and a clear deletion path at termination.

Commercial terms are structured rather than hidden. Flexible commercial structures are normal in this category and there is nothing wrong with them, provided the operator can see the whole picture and it does not create an incentive to narrow the resident’s options.

Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services and insurance verification directly into the workflow.

Frequently asked questions

Is there anything wrong with a vendor earning from resident services?

No. Residents buy movers, packing, storage, and insurance during every move. A vendor earning by delivering those services well is aligned with both the operator and the resident. The concern is a model where the earnings come from access to the resident rather than from service delivery, because that decouples the vendor’s incentive from the resident’s outcome.

How do we evaluate this without a procurement team?

Three documents answer most of it: the full revenue model in writing, the data processing terms, and the service level commitments with named remedies. If a vendor will not put the revenue model in writing, that is the finding.

Does paying for software actually change the incentive?

It changes who the vendor answers to. When the operator is the paying customer, the operator sets the service standard and can enforce it. That is the practical difference, and it is why the question of who pays is worth asking before the demo rather than after.

We are mid-contract. What can we do now?

Ask for the revenue model in writing and review your data terms at the next renewal window. Most agreements have a notice period that makes this a planning question rather than an emergency.

Closing

Free software is a pricing decision the vendor made, and it tells you where their revenue comes from. For an operator managing 10,000 units or more, the real test is whether the arrangement keeps the operator, the vendor, and the resident pointed in the same direction, and whether the operator can explain it plainly if a regulator, an owner, or a resident asks.

If you want a structured review of what your current move-in vendor arrangement actually commits you to, reach out to our team.

Related reading: how the move-in and move-out process generates revenue for property managers, and the complete guide to resident onboarding automation. See also Moved for multifamily operators and the resident experience.

The notice-to-vacate window most operators never monetize

A resident submits notice to vacate. Inside most multifamily operating platforms, that single action sets off a well-instrumented cost sequence. The unit enters the make-ready queue. Turn vendors are scheduled. The revenue management system starts pricing the vacancy. Someone begins counting days.

What almost never starts is a revenue process.

This is the one moment in the entire resident lifecycle where an operator knows, with near certainty, that a household is about to spend money on moving services. The resident is going to hire movers. They are going to buy packing materials. Some of them will need storage. Most of them will need insurance at the next address. All of that purchasing happens inside a window the operator opened and can see, and almost all of it happens somewhere the operator cannot see.

The window is already the most instrumented moment in your portfolio

Operators measure this period closely, because the costs are severe and well understood.

Turn costs have been climbing. The National Apartment Association reported that leasing expenses reached $292 per unit in 2024, “largely driven by a 17.5% increase in turnover costs year-over-year” (NAA Income/Expense IQ 2024 National Summary). On the individual turn, Zego’s Resident Experience Management Report, published through NAA, put the cost at “$4,000 per unit, which includes lost rent, concessions and maintenance.”

The vacancy side has moved against operators as well. RealPage Analytics found that “nationwide, average vacant days hovered at 34.4 at the end of 2024, compared to about 30 in early 2020,” and noted that “with more than half a million stabilized units unoccupied, the additional impact to property operations quickly adds up.”

So the window is not an unknown. Every operator at 10,000 units and above already has dashboards pointed at it. The instrumentation exists. It is pointed exclusively at cost.

Why the revenue side stays invisible

Three things make this window commercially blind for most operators in residential real estate.

The first is timing. Notice arrives through a portal, an email, or a conversation with a leasing associate. It creates a task. It does not create an offer. By the time anyone in the organization is thinking commercially about that household, the household has already booked a mover.

The second is ownership. Move-out sits between departments. Leasing owns the new lease. Maintenance owns the turn. Accounting owns the deposit. Nobody owns the departing resident as a customer, so nobody is accountable for what that customer buys.

The third is measurement. If revenue in this window is never captured in a system of record, it never appears in a report, and a category that never appears in a report never gets a target. The absence becomes self-sustaining.

What the departing household is actually buying

The commercial content of this window is concrete, and it is dominated by moving services.

Movers come first. This is the largest single purchase most households make during a move and the one with the tightest booking window. Packing services and materials attach directly to it. Storage attaches for the subset of households whose move-out date and move-in date do not line up, which is a common pattern in urban portfolios.

Insurance sits alongside those services as a financial risk mitigation item rather than a convenience. A departing resident needs coverage at the next address, and the operator receiving that resident needs verified coverage in place before keys change hands. Handled as an afterthought, this becomes a compliance chase after occupancy. Handled inside the move workflow, it becomes a condition of the move itself.

Utilities and connectivity follow the same pattern. Both are service decisions the resident has to make anyway, on a schedule the operator already controls.

None of these are new services. They are purchases that already happen on a predictable schedule, inside a window the operator opens. The question is whether the operator participates in them or watches them leave.

The retention argument runs through the same window

Retention is unusually strong right now, which changes the economics of every move that does happen. RealPage Analytics reported that “just over 54% of renters in market-rate apartments renewed their leases in the year-ending October 2024, amounting to a 120 basis point (bps) climb over last year.”

Large operators are seeing the same pattern in their own portfolios. Multifamily Dive reported Essex Property Trust’s CEO describing “a notably low turnover rate of 35%, while achieving positive new lease rate growth and stable occupancy levels,” MAA “reported improving turnover at 41.5% in Q1,” and Camden’s Keith Oden saying “our first quarter 2025 annualized net turnover rate of 31% was one of the lowest in our company’s history.”

Fewer moves means each remaining move carries more weight. It also means the quality of the move-out experience feeds directly back into reputation and referral, which feed back into the next lease-up.

This is also where resident-facing programs belong in the conversation. Paylode, which became a Moved company through an acquisition in November 2025, exists to make resident perks and offers a structured part of the operator’s relationship with the household rather than a scattering of one-off discounts. In the move-out window, that structure is what turns a service offer into something a resident actually accepts.


What this looks like when it is built properly

At 10,000 units and above, this has to be a system rather than a set of instructions to site teams. A few design requirements follow from that.

Notice has to trigger an offer, automatically, in the same motion that it triggers the make-ready task. If the trigger depends on a leasing associate remembering, the program will work at some communities and fail at others, and the portfolio-level number will never move.

The offer has to be the same everywhere. Portfolio-wide consistency is what makes the revenue measurable and what makes vendor economics work. A different arrangement at every region produces a number nobody can report on.

Every transaction has to land in a system of record, attributed to the property and the move event. Revenue that cannot be attributed cannot be reported, and revenue that cannot be reported has no standing with an asset management team.

And the move-in and move-out sides have to be treated as one workflow rather than two, because the household leaving one of your communities is frequently the household arriving at another, and the same services apply at both ends.

Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services and insurance verification directly into the workflow.

What to measure

Four things tell you whether the window is actually working.

Offer rate: the share of notices that produced a service offer inside the window. This is the honest test of whether the trigger is automated. Anything materially below full coverage means the process still depends on memory.

Time from notice to first offer. The mover booking decision happens early. An offer that arrives a week after notice is competing against a decision the household has already made.

Attach rate by service, tracked separately for movers, packing, storage, insurance, utilities and connectivity. A single blended number hides which part of the workflow is failing.

Consistency across the portfolio. Compare the spread between your best-performing region and your worst. A wide spread is a process problem rather than a market problem.

Where to start

Pull one quarter of notices across the portfolio and answer a single question for each: what did this household buy, and did we see any of it. Most operators cannot answer for the majority of records, and the size of that blind spot is the finding.

From there the sequence is straightforward. Automate the trigger off the notice event. Standardize the offer set across every region. Put the transactions into a system of record. Then measure the four numbers above and hold them at the portfolio level rather than the property level.

Frequently asked questions

Is this the same as charging residents more fees?

No. The services described here are purchases the household is already making with an outside provider. The change is that the operator participates in a transaction that is happening anyway and takes responsibility for its quality. Regulatory attention on rental fee disclosure is increasing, which makes the distinction between a mandatory charge and an optional service the resident chooses more important, not less.

Does this slow down the turn?

Handled inside the workflow, it does the opposite. Coordinated move-out scheduling, confirmed key return, and booked elevator or loading dock time all reduce the resident-driven delays that push vacant days up.

We already offer some of this at a few communities. Why change anything?

Property-level programs produce property-level results. The reason to systematize is that a portfolio number only exists when the trigger, the offer set, and the reporting are identical everywhere. Without that, there is nothing for an asset management team to underwrite.

What about residents who do not want to be sold anything?

The offer should be genuinely optional and clearly presented. The service quality standard matters here as well, because the operator’s name is attached to whoever shows up on moving day.

Closing

The notice-to-vacate window is already the most closely watched period in the resident lifecycle. The instrumentation exists. The dates are known. The household’s purchasing intent is as clear as it will ever be. What is missing is a commercial process pointed at the same window the cost process already occupies.

If you manage 10,000 units or more and want to see what your notice-to-vacate window currently produces, reach out to our team to walk through it with your own data.

Related reading: how operators turn the move-in and move-out process into a revenue workflow, and the complete guide to resident onboarding automation. For how this shows up on the resident side, see Moved for residents, and for the operator view, see Moved for multifamily.

The FTC rental fee rulemaking: what operators must disclose on move-in charges

  For 10,000+ unit operators, the move-in moment is where a large share of non-rent revenue is created. Application fees, administrative fees, amenity charges, package and utility setup, insurance verification, and the paid moving services a resident selects all land in the same window. That window is now the subject of a federal rulemaking, and the way charges are disclosed at move-in is about to move from a matter of preference to a matter of compliance.

On March 12, 2026, the Federal Trade Commission announced an Advance Notice of Proposed Rulemaking on unfair or deceptive rental housing fee practices, published in the Federal Register on March 13, 2026. The notice asks whether the FTC should require full, upfront disclosure of every mandatory charge before a renter applies for or commits to a lease, and it covers the entire rental lifecycle from application through move-out. Public comments were due April 13, 2026. This article explains what the rulemaking means for the charges you process at move-in, and how to keep that revenue while staying on the right side of the disclosure standard.

What the FTC is actually proposing

The rulemaking targets charges that are not clearly disclosed upfront or that bear no reasonable relationship to the underlying cost of the service. According to the law firm Katten Muchin Rosenman, the notice specifically names application fees, administrative fees, convenience charges, and amenity fees as categories under review, and it contemplates a federal framework for rental fee transparency across the transaction. The full analysis is set out in Katten’s client alert on the proposed rule.

The intent is consumer protection. As the law firm Covington summarized in its Inside Privacy review of the ANPRM, the FTC is evaluating whether hidden or poorly explained charges constitute deceptive practices, as part of a wider federal campaign against so-called junk fees. The direction of travel is clear even before a final rule exists.

The pressure is not federal alone. In April 2026, a bipartisan coalition of state attorneys general, led by New York Attorney General Letitia James, urged the FTC to act on deceptive rental fees. Operators face a converging federal and state expectation that every charge is named, explained, and shown before a resident is asked to commit.

Why this lands hardest at the move-in moment

Disclosure obligations are easy to state and hard to operationalize when charges are scattered across a leasing team, a payments processor, an insurance vendor, and a moving partner. The move-in window is where those charges converge, so it is also where a disclosure gap is most likely to appear. A resident who sees an amenity fee or a utility activation charge for the first time on move-in day is exactly the scenario the rulemaking is written to address.

This is a revenue question before it is a compliance question. Non-rent charges at move-in are a core part of how operators in residential real estate build income beyond rent, and the move-in and move-out revenue workflow is where that income is captured. The risk is not that disclosure rules eliminate these charges. The risk is that a disorganized move-in process forces you to defend a charge you could have simply disclosed cleanly. Protecting the revenue and meeting the standard are the same project.

The compliance exposure, framed as financial risk

Undisclosed or poorly documented fees create measurable financial risk. An enforcement action, a state attorney general inquiry, or a class claim over a single fee type repeated across a 10,000+ unit portfolio is a liability that scales with the size of the book. Renters insurance sits inside this same risk picture. Requiring coverage protects the asset from resident-caused loss, and verifying that coverage at move-in is the point where enforcement is frictionless. A move-in process that captures insurance verification and discloses every charge in one flow turns two separate liabilities into one controlled step.

The paid services a resident chooses during move-in, including movers, packing, and storage, belong on the same disclosed ledger. When these are presented as clearly optional resident selections with transparent terms, they support the resident experience and stay well clear of the mandatory-fee definitions the FTC is scrutinizing. Clean separation of mandatory charges from optional services is one of the strongest protections available under the proposed standard.

What a disclosure-ready move-in looks like

Operators that will adapt fastest share one trait: their charges live inside a single move-in and move-out workflow rather than across disconnected tools. A disclosure-ready process presents every mandatory charge before the resident commits, separates optional services from required fees, timestamps what was shown and when, and produces a record an operator can stand behind if a charge is ever questioned.

Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services and insurance verification directly into the workflow, which is what makes clean disclosure possible at scale. When the charge, the disclosure, and the record are one system rather than three, compliance stops being a manual audit and becomes a property of the process. For operators standardizing this across a portfolio, the guide to resident onboarding automation covers how the workflow is built.

A practical checklist for portfolio operators

Ahead of any final rule, four moves reduce exposure now. First, inventory every charge a resident can incur from application through move-out and label each as mandatory or optional. Second, confirm each mandatory charge is disclosed before the resident commits, not on move-in day. Third, verify that the amount of each fee has a documented relationship to the cost of the service it covers. Fourth, keep a durable record of what was disclosed to whom and when. A move infrastructure built for multifamily operators produces that record automatically as part of the move-in and move-out flow.

Frequently asked questions

Is the FTC rule final?

No. As of the April 13, 2026 comment deadline it is an Advance Notice of Proposed Rulemaking. The FTC may proceed to a proposed rule or take no further action, but the disclosure expectation is already being reinforced by state attorneys general.

Does this ban move-in fees?

No. The rulemaking targets charges that are hidden, unexplained, or unrelated to the cost of the service. Clearly disclosed charges tied to a real service are the intended safe path.

What about optional services like movers, packing, and storage?

furthermore optional resident selections with transparent terms are treated differently from mandatory fees. The key is presenting them as genuine choices and keeping them separate from required charges.

How does insurance verification fit in?

Requiring and verifying renters insurance at move-in is risk mitigation for the asset, and doing it inside the move-in and move-out workflow keeps enforcement clean and documented.

Get ahead of the standard

The operators who will handle this rulemaking comfortably are ones who disclose cleanly because their move-in and move-out charges already run through one workflow. If you want to see how  single move infrastructure captures every charge, verifies insurance, and produces a defensible disclosure record across a 10,000+ unit portfolio, contact Moved to walk through it.

Resident-side turn delay the move-out days your vendor scorecard never sees

Every large operator measures turn. Days to make ready, vendor speed, cost per turn, and quality scores are tracked closely because turn time is one of the most expensive variables in the portfolio. Apartment turnover costs have held steady at about $3,872 per turn, according to Zego’s Resident Experience Management Report as covered by Multifamily Dive, a figure drawn from 630 property managers of communities with 250 or more units. That number captures the vendor side of turn well. It misses a second source of delay entirely.

There is a stretch of the turn that no vendor scorecard measures, because no vendor controls it. It is the resident-driven half: how quickly notice is processed, how the move-out is scheduled, whether keys and fobs come back on time, and whether the dock and elevator were booked so the outgoing move and the incoming move do not collide. Call it resident-side turn delay. It sits before your make-ready crew ever gets the unit, and for most operators it is invisible.

Why the resident side of turn is unmeasured

Turn measurement starts when maintenance takes possession of an empty unit. Everything that happens before that point is treated as a fixed input rather than a managed process. But the days between a resident giving notice and maintenance actually starting are real vacancy days, and they are just as expensive as the days your crew is painting.

The reason this half goes unmeasured is structural. Notice handling lives in the property management system. Move-out scheduling lives in an email thread or a leasing office conversation. Key return lives on a hook behind the front desk. Dock and elevator booking, where it exists at all, lives in a building calendar. Because the resident side of turn is spread across four disconnected places, no single number ever adds it up. What is not measured does not get managed, and what is not managed drifts.

Where the delay actually accumulates

Resident-side turn delay compounds in a few predictable places. Notice that arrives by phone or email and is entered late starts the clock late. A move-out that is never formally scheduled leaves the outbound date uncertain, so the make-ready plan cannot be sequenced. Keys and access fobs that come back a day or two after the resident has physically gone leave the unit legally occupied and untouchable. And in buildings with a single freight elevator, an unbooked move-out can block the move-in of the next resident, adding days that appear nowhere in a vendor report.

None of these are maintenance failures. They are coordination failures, and coordination is exactly the part of the move that operators have historically left to chance. This is the resident-driven mirror of the well-run move-in and move-out revenue workflow: the same window that generates non-rent revenue also determines how fast a unit turns.

The revenue view comes first

Before the efficiency story, there is a revenue story. The move-out is not only a cost event to be minimized. It is a revenue event to be captured. A resident who schedules a move-out through a guided flow is a resident you can offer movers, packing, and storage to at the exact moment those services are relevant, which supports both the resident experience and the operator’s non-rent income. The same coordinated flow that shortens the turn also opens the paid-services window. Treating move-out purely as a maintenance trigger leaves that revenue on the table.

This is the difference between managing turn as a cost and managing the move as an asset. When the resident side of the move-out is a real workflow, it earns revenue and shortens vacancy in the same motion. 

Naming the metric so you can manage it

A category gets managed once it has a name and a number. Resident-side turn delay can be measured as the elapsed time between notice received and unit ready for make-ready, broken into its parts: notice-to-entry lag, scheduling lag, key-return lag, and access-booking lag. Once those four are visible, they can be targeted the same way vendor turn time already is.

The metric matters most at scale. Across a 10,000+ unit portfolio, a two-day average resident-side delay is thousands of avoidable vacancy days a year that never appear on a single vendor scorecard. Operators in residential real estate already accept that turn time drives rent growth. Extending that discipline to the resident-driven half is the next available gain, and it is one competitors have not named.

How the coordination gets closed

Closing resident-side turn delay means putting the four scattered pieces into one flow. Notice is captured digitally and starts the clock immediately. Move-out is scheduled by the resident inside a guided process. Key and fob return is tracked against that schedule. Dock and elevator booking is part of the same step, so the outbound and inbound moves are sequenced rather than colliding. Insurance status is confirmed in the same flow, which keeps the asset protected through the move-out and mitigates the financial risk of an uninsured resident-caused loss on the way out.

Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services and insurance verification directly into the workflow, which is why the same system that captures move-out revenue also produces the timing data that makes resident-side delay visible. Operators standardizing this across a portfolio can see how the flow is built in the guide to resident onboarding automation, and how a move infrastructure built for multifamily operators unifies the pieces.

Frequently asked questions

Is resident-side turn delay a standard industry metric?

Not yet. Most operators measure only the vendor and make-ready side of turn. The resident-driven days before make-ready begins are real vacancy days that typically go uncounted.

How is it different from normal turn time?

Normal turn time starts when maintenance takes an empty unit. Resident-side turn delay measures the coordination lag before that point: notice handling, move-out scheduling, key return, and dock or elevator booking.

Does fixing it really move the number at portfolio scale?

Yes. Small per-move delays multiply across thousands of turns a year, so even a one or two day average reduction removes a large block of avoidable vacancy days.

How does move-out revenue fit into turn?

A guided move-out lets you offer movers, packing, and storage when they are relevant, so the same coordinated flow that shortens the turn also captures non-rent revenue.

See the half of turn you are missing

If your turn reporting stops at the vendor scorecard, the resident-driven days are still costing you and you cannot see them. To measure resident-side turn delay across your portfolio and close it inside a single move-in and move-out workflow, contact Moved.


Turning resident perks into a measurable revenue line

Most operators run some form of resident perks. Discounts on local services, partner offers, rewards for on-time payment, and renewal incentives show up across the portfolio in one form or another. Almost none of it is measured as revenue. Perks are treated as a soft retention gesture, funded out of a marketing line, and reported as goodwill rather than a number that moves net operating income. That is the missed opportunity. A perks program that is instrumented correctly is a measurable revenue line, and it sits directly on top of the move-in and move-out moments operators already control.

This matters more in a market where rent alone will not carry the year. With rent growth decelerating and operating costs still climbing, the revenue that closes the gap is increasingly the non-rent kind. Retention is part of that math too. Apartment turnover costs have held steady at about $3,872 per turn, according to Zego’s Resident Experience Management Report as covered by Multifamily Dive. Every renewal a perks program earns is a turn cost you do not pay, and every partner offer a resident redeems can be a revenue event you can count.

Paylode is a Moved company

Moved acquired Paylode in November 2025, and Paylode is now a Moved company. That matters here because Paylode is a resident perks and loyalty platform built for exactly this problem: turning everyday resident engagement and partner redemptions into a structured, trackable program rather than a scattered set of one-off discounts. The Paylode loyalty rewards platform for multifamily is designed to recognize resident actions such as on-time payment, renewals, and community engagement, and to make the resulting value visible. Combining that perks engine with Moved’s move-in and move-out infrastructure gives operators a first-party path from the move itself to a measured perks line that no single-service vendor can match.

Why perks stay invisible as revenue

Perks fail to register as revenue for a simple reason: they are not connected to a transaction record. A discount handed out at the leasing office, an offer emailed to residents, or a reward mentioned at renewal has no structured trail. Nobody can say how many residents redeemed it, what it drove, or what it returned. Without that trail, finance has no choice but to treat perks as a cost of goodwill.

The fix is to attach perks to moments that are already instrumented. The move-in and move-out window is the most instrumented moment in the resident lifecycle, and it is where perks become measurable. A partner offer presented during move-in, a reward tied to an on-time renewal, or a redemption captured inside the resident flow all produce a record. Once there is a record, there is a number, and once there is a number, perks become a revenue line the CFO can underwrite.

The move is where perks get their record

The move-in and move-out flow is the natural home for a perks program because the resident is already transacting. During move-in a resident is selecting services, confirming details, and setting up their new home, so a relevant partner offer lands in context rather than as noise. The same is true at renewal and at move-out. The move-in and move-out revenue workflow already captures the moment; adding perks to it means every redemption is tied to a resident, a date, and an outcome.

This is also where paid services and perks reinforce each other. A resident choosing movers, packing, or storage during the move can be met with a partner reward that improves the resident experience and encourages the next action. The perk is no longer a standalone discount. It is part of a flow that already generates non-rent revenue, and it is measured the same way.

What a measurable perks line requires

Turning perks into a revenue line takes four things. First, a single catalog of offers and rewards so residents see a consistent program rather than a patchwork. Second, redemption tracking so every use is recorded against a resident. Third, attribution to the moment, so you can tell which perks earned renewals or drove service uptake. Fourth, ownership by one team that reports the number, the same way any other income line is owned. A perks program with those four properties reports like revenue because it is revenue.

Insurance belongs in this picture as risk mitigation. Verifying renters insurance inside the same resident flow protects the asset from resident-caused loss, and doing it alongside perks keeps the entire relationship inside one instrumented workflow. Operators in residential real estate that unify perks, paid services, and insurance verification in one flow get a resident experience that is both richer and fully accountable.

Standardizing it across the portfolio

The value shows up at scale. A perks program that is run property by property produces inconsistent offers and no portfolio number. Run as one catalog across a 10,000+ unit book, it produces a single measurable line and a consistent resident experience everywhere. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services and insurance verification directly into the workflow, and with Paylode inside that workflow the perks program becomes part of the same measured system. Operators can see how the underlying flow is built in the guide to resident onboarding automation, and how a move infrastructure built for multifamily operators ties perks to the move.

Frequently asked questions

Are resident perks really a revenue line, or just retention? 

They are both. Redeemed partner offers can be counted as revenue events, and the renewals perks drive avoid turn costs that hold near $3,872 per turn. Instrumented correctly, perks show up in both places.

What is Paylode and how does it relate to Moved? 

Paylode is a resident perks and loyalty platform, and it is a Moved company following the November 2025 acquisition. It provides the perks engine that pairs with Moved’s move-in and move-out infrastructure.

Why tie perks to the move-in and move-out moment? 

Because that moment is already instrumented. Attaching perks to it produces a record for every redemption, which is what turns perks from goodwill into a measured number.

How do perks and paid services work together?  

During the move a resident is already choosing services like movers, packing, and storage, so a relevant reward lands in context and can be measured alongside those selections.

Make your perks program count

If your perks are funded like a cost and reported like goodwill, you are running a revenue line without measuring it. To turn resident perks into a tracked, portfolio-wide number using Paylode inside Moved’s move-in and move-out workflow, contact Moved.

Why “Free” Move-In Platforms Are Not Free: Take Rates, Steering, and Who Owns the Resident Relationship

A move-in platform that costs the operator nothing sounds like an easy decision. For a 10,000+ unit operator, it is worth asking a harder question first: free to whom? The move-in and move-out window generates real revenue and sits on the resident relationship, and both usually fund a platform that is free to the operator. This guide lays out where the money in a free model actually comes from, and the three questions an operator should ask before deciding. We cover the broader operating model in our guide to ancillary revenue in multifamily.

Where the money in a free model comes from

No platform runs on nothing. When a resident moves, they buy movers, packing, storage, utilities, internet, and insurance, and every one of those transactions can pay a referral or partnership fee. A platform that charges the operator nothing is funded by the take rate on those resident transactions, and often by the value of owning the resident relationship and the data around the move. Free to the operator can quietly mean the operator hands over the ancillary revenue and the resident relationship in exchange for a service that looked like it had no cost.

That is not an argument against convenience. It is an argument for knowing which side of the ledger the value lands on, because at portfolio scale the move-in and move-out window is a revenue line, not a rounding error.

Three questions to ask before choosing

Who captures the take rate?

The move generates ancillary revenue whether the operator captures it or not. The first question is simple: when a resident buys movers, storage, or insurance through the platform, does that revenue flow to the operator or to the platform? A model that keeps the revenue with the operator treats the move as the operator’s asset. A model that keeps it with the platform treats the operator’s resident as the platform’s inventory.

Who steers the resident?

Every move platform makes recommendations. The second question is whether the resident is guided to the option that serves them best or the option that pays the platform most. Steering that optimizes for the platform’s take rate rather than the resident’s outcome shows up later as a weaker resident experience, and the operator carries that even when the platform booked the revenue.

Who owns the resident relationship?

The move is one of the highest-trust moments in the resident lifecycle. The third question is who owns that relationship and the data around it. A platform that intermediates the resident relationship is building its own asset on the operator’s residents. An operator that keeps the relationship keeps the retention, the brand, and the data that informs the next decision.

The alignment an operator should want

The model that works for a 10,000+ unit operator is the one where the operator captures the revenue, sets the standard for how residents are served, and owns the resident relationship, while still giving residents a genuinely convenient move. Convenience and ownership are not in tension when the commercial structure is built to align with the operator’s financial goals rather than around a take rate on the operator’s residents. We walk through the mechanism in our breakdown of how move-in and move-out workflows became a property management revenue engine and the onboarding mechanics in our ultimate guide to resident onboarding automation.

What the revenue is worth

The reason this decision matters is that the revenue is real. The uncaptured non-rent opportunity sits at roughly $15 per unit per month, per the Moved CEO’s RevGen leak map, most of it concentrated in the move-in and move-out window. A free platform that captures that revenue for itself is not free. It is the operator paying with the exact revenue line it should be building.

Why "Free" Move-In Platforms Are Not Free: Take Rates, Steering, and Who Owns the Resident Relationship

How Moved fits

Moved is the move-in and move-out infrastructure platform built so the operator captures the value. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services, including movers, packing, storage, utilities, internet, and insurance verification, directly into the resident workflow, and returns the revenue and the resident relationship to the operator rather than intermediating them. Resident perks, rewards, and partnerships run on Paylode, a Moved company that Moved acquired in November 2025 to advance ancillary revenue automation, per the Moved announcement. The resident-facing experience lives inside the Moved resident experience. Moved is built on flexible commercial structures designed to align with property financial goals.

To see a model where the operator captures the move, book a walkthrough with our team or visit the Moved multifamily product page.

FAQs

Why is a free move-in platform not really free?
Because it is funded by the take rate on resident move transactions and by owning the resident relationship and data. Free to the operator can mean giving away the ancillary revenue and the relationship.

What is a take rate?
The fee a platform earns on the resident’s move transactions, such as movers, storage, or insurance. The question is whether that fee flows to the operator or the platform.

What is steering?
Guiding the resident toward the option that pays the platform most rather than the one that serves the resident best, which weakens the resident experience the operator carries.

Why does owning the resident relationship matter?
Because the move is a high-trust moment, and keeping the relationship keeps the retention, brand, and data with the operator instead of the platform.

Can an operator have convenience and ownership?
Yes, when the commercial structure is built to align with the operator’s financial goals rather than around a take rate on the operator’s residents.

The bottom line

In residential real estate, a free move-in platform is a pricing question wearing a convenience costume. Before choosing one, a 10,000+ unit operator should ask who captures the take rate, who steers the resident, and who owns the relationship, because the move-in and move-out window is a revenue line worth keeping.

For the NOI picture, see our guide to increasing multifamily NOI without raising rent.

Centralized Ancillary Revenue: One Catalog, One Team, One Standard Across the Portfolio

Centralization is the live operational conversation at 10,000+ unit operators, and it is almost always told as a staffing story: fewer people at the property, more work run from a central team. There is a revenue side of centralization that the conversation skips, and it is where the move-in and move-out window turns into a portfolio-wide number. Centralizing ancillary revenue means one catalog, one team, and one standard across every property. We cover the broader operating model in our guide to ancillary revenue in multifamily.

This guide lays out why decentralized ancillary revenue underperforms and what it means to centralize the revenue side the way operators are already centralizing leasing.

The revenue side centralization forgets.

Operators are centralizing operations at scale, with Funnel Leasing finding that 80% of third-party multifamily managers are centralizing. Almost all of that energy goes to leasing and staffing. Meanwhile,e the ancillary revenue that lives in the move-in and move-out window is still run property by property, with each site choosing its own services, its own partners, and its own approach. Centralization has reached the cost side of operations and left the revenue side decentralized.

That is a mismatch. The same central structure that standardizes leasing can standardize the revenue the move generates, and until it does, non-rent revenue stays as inconsistent as the properties that run it.

What decentralized ancillary revenue costs

When every property runs its own version of the move offer, the portfolio pays for the inconsistency.

  • Attach rates swing property to property, because the offer, the partners, and the presentation differ at every site.
  • Margin is left on the table where a property picked a weaker partner or a worse structure than the portfolio could negotiate centrally.
  • Compliance and the resident experience vary site to site, which raises risk and erodes brand.
  • The asset management team cannot compare or improve the number, because there is no single standard to measure against

The fix: centralize the revenue like the leasing

Centralizing ancillary revenue means applying the same central structure operators use for leasing to the revenue side of the move-in and move-out window.

  • One catalog. The same set of services, movers, packing, storage, utilities, internet, and insurance, offered at every property, so residents get a consistent menu and the portfolio negotiates as one buyer.
  • One team. A central team owns the non-rent revenue number across the portfolio, with a target and a dashboard, instead of the number living in hundreds of site-level decisions.
  • One standard. The same offer presented the same way at the move-in and move-out window, so attach rates stop depending on which property a resident happens to live in.

We detail the mechanism in our breakdown of how move-in and move-out workflows became a property management revenue engine and the onboarding mechanics in our ultimate guide to resident onboarding automation.

What it captures at portfolio scale

Centralized, the ancillary revenue that a decentralized approach leaves scattered becomes one managed number that the whole portfolio moves together. The uncaptured non-rent opportunity sits at roughly $15 per unit per month, per the Moved CEO’s RevGen leak map, and the gap between the best and worst properties is exactly what one catalog, one team, and one standard close can close.

Infographic - The Compliance-First Move-In and Move-Out Workflow

How Moved fits

Moved is the move-in and move-out infrastructure platform that gives the central team one catalog and one standard to run. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services, including movers, packing, storage, utilities, internet, and insurance verification, directly into the resident workflow, presents the same offer at every property, and returns the results to the central team as category-level data by property, stream, attach rate, and margin. Resident perks, rewards, and partnerships run on Paylode, a Moved company that Moved acquired in November 2025 to advance ancillary revenue automation, per the Moved announcement. The resident-facing experience lives inside the Moved resident experience. Moved is built on flexible commercial structures designed to align with property financial goals.

To centralize the revenue side of the move, book a walkthrough with our team or visit the Moved multifamily product page.

FAQs

What is centralized ancillary revenue?
Running the non-rent revenue side of the move-in and move-out window from a central structure, with one service catalog, one team that owns the number, and one offer standard across every property.

How is it different from centralized leasing?
Centralized leasing addresses the cost and staffing side of operations. Centralized ancillary revenue applies the same structure to the revenue the move generates.

Why does decentralized ancillary revenue underperform?
Because every property runs its own offer, partners, and presentation, so attach rates and margin swing site to site, and the number cannot be managed as a whole.

What are the three pieces?
One catalog of services offered everywhere, one central team that owns the number, and one standard for how the offer is presented at the move-in and move-out window.

Who owns the centralized number?
A central team at the asset management or operations layer, with a target and a dashboard, supported by on-site execution.

The bottom line

In residential real estate, centralization has reached leasing and stopped short of revenue. Extending it to ancillary revenue, one catalog, one team, and one standard across the portfolio turns the move-in and move-out window from hundreds of site-level decisions into a single managed number the whole book moves together.

For the NOI picture, see our guide to increasing multifamily NOI without raising rent.

Notice to Vacate: The 60-Day Window Most Operators Never Monetize

When a resident submits a notice to vacate, most 10,000+ unit operators start a clock on cost. The turn is coming, the make-ready has to be scheduled, and the unit has to be re-leased. What the notice actually opens is a 60-day window, and it is one of the most valuable and least managed windows in the entire move-in and move-out lifecycle. We cover the broader operating model in our guide to ancillary revenue in multifamily.

This guide reframes the notice-to-vacate date from the start of a cost into the start of a revenue, retention, and compliance window, and lays out the standardized move-out workflow that captures it.

The moment everyone treats as a cost

The notice to vacate is the first confirmed signal that a resident is moving. From that date, the resident begins deciding about movers, packing, storage, utility transfers, and insurance for the new home, and those decisions happen whether or not the operator is present for them. Most operators are not present. They log the notice, queue the turn, and let 60 days of high-intent resident activity pass by as a purely administrative countdown to a vacant unit.

That is the miss. The same 60 days that the operator spends preparing for cost are the days the resident is actively spending on the move. The move-out side of the move-in and move-out window is a revenue window that opens the moment the notice lands.

What the unmanaged window leaks

Left as an administrative countdown, the notice-to-vacate window leaks value in several ways at once.

  • Move-related ancillary revenue goes uncaptured, because no one surfaces movers, packing, storage, and insurance to the departing resident at the moment they are deciding.
  • The resident-side turn drifts, as move-out scheduling, key return, and dock or elevator booking happen ad hoc rather than on a managed timeline.
  • Retention and transfer opportunities are missed, because a resident moving locally is a candidate to stay inside the portfolio, and no one is having that conversation.
  • Compliance and insurance verification lapse before the last day, raising exposure at exactly the wrong moment

The fix: a workflow that triggers at notice

Capturing the window means treating the notice to vacate as a trigger that starts a standardized move-out workflow, the same way move-in is triggered at lease signing.

  • The workflow surfaces movers, packing, storage, utilities, and insurance to the departing resident at the moment of decision, capturing the move-related revenue that otherwise leaves.
  • It coordinates the resident-side turn, move-out scheduling, key return, and dock or elevator booking, on a managed timeline so make-readies do not fall behind.
  • It surfaces transfer and renewal options to residents moving locally, turning some move-outs into retained revenue.
  • It holds insurance verification and documentation in force through the last day.

We detail the mechanism in our breakdown of how move-in and move-out workflows became a property management revenue engine and the onboarding mechanics in our ultimate guide to resident onboarding automation.

What it captures at portfolio scale

Run consistently, a notice-triggered workflow captures the move-related revenue the departing resident generates, coordinates the turn so cost comes down, and keeps some residents inside the portfolio. The uncaptured non-rent opportunity sits at roughly $15 per unit per month, per the Moved CEO’s RevGen leak map, and much of the move-out share of it lives in this window. On the cost side, turnover already runs close to $3,872 per resident, per Multifamily Dive, so a coordinated resident-side turn improves both halves of the ledger.

Infographic - Notice to Vacate

How Moved fits

Moved is the move-in and move-out infrastructure platform that acts on the notice-to-vacate window. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services, including movers, packing, storage, utilities, internet, and insurance verification, directly into the resident workflow, and triggers the move-out flow at notice so the window is captured rather than counted down. Resident perks, rewards, and partnerships run on Paylode. Moved was acquired in November 2025 to advance ancillary revenue automation, per the Moved announcement, which is what powers the retention and transfer side of the window. The resident-facing experience lives inside the Moved resident experience. Moved is built on flexible commercial structures designed to align with property financial goals.

To turn the notice-to-vacate window into a managed workflow, book a walkthrough with our team or visit the Moved multifamily product page.

FAQs

What is the notice-to-vacate window? It is the roughly 60-day period between a resident submitting notice and moving out, when the resident is actively making move decisions the operator can capture.

Why do most operators miss it? Because they treat the notice as the start of a turn cost and let the window pass as an administrative countdown rather than a revenue and retention opportunity.

What does a notice-triggered workflow do? It surfaces move services at the moment of decision, coordinates the resident-side turn on a managed timeline, surfaces transfer options, and holds compliance through the last day.

How does it affect turnover cost? Coordinating move-out scheduling, key return, and dock or elevator booking keeps make-readies on track, which helps control the cost of the turn.

Can it help retention? Yes. A resident moving locally is a candidate to transfer within the portfolio, and the workflow surfaces that option instead of letting the resident leave the book.

The bottom line

In residential real estate, the notice to vacate is not the start of a cost; it is the opening of a window. Triggering a standardized move-out workflow at notice captures the revenue the departing resident generates, coordinates the turn, and keeps some residents inside the portfolio, across the most under-managed 60 days in the move-in and move-out lifecycle.

For the NOI picture, see our guide to increasing multifamily NOI without raising rent.

How Enterprise Multifamily Operators Automate Move-In and Move-Out Across Yardi, RealPage, and Entrata

An enterprise operator running 30,000 or more units rarely runs a single property management system. Acquisitions, regional preferences, and legacy deployments leave most large portfolios on a mix of Yardi, RealPage, and Entrata. The move-in and move-out workflow, where the highest-intent resident revenue and the sharpest experience moments sit, has to run consistently across all of them. We cover the broader operating model in our guide to ancillary revenue in multifamily.

This guide explains why a mixed property management system fragments the move-in and move-out experience, and how a move layer that integrates with each platform delivers a standardized workflow across the whole portfolio without a rip-and-replace.

Why a mixed PMS estate fragments the move

Each property management system handles the resident lifecycle a little differently, so for an enterprise operator, the move-in and move-out experience is defined by whichever system a given property happens to run. A resident onboarding into a Yardi property gets one experience; a resident in a RealPage property, another; and a resident in an Entrata property, a third. Multiply that across tens of thousands of units, and the operator has no single standard for the most valuable moment in the resident lifecycle.

Ripping and replacing the property management system to fix this is off the table. These platforms are the system of record for leasing, accounting, and operations, and consolidating them across a large portfolio is a multi-year project no operator wants to run just to standardize the move.

What fragmentation costs at enterprise scale

Running the move-in and move-out windows differently across platforms leaks value in three ways at once.

  • Ancillary revenue is captured on some platforms and missed on others because the offers for movers, storage, utilities, internet, and insurance depend on the underlying system rather than a single standard.
  • Compliance and insurance verification are inconsistent across the estate, which raises exposure at scale.
  • The resident experience varies by property for reasons the resident never sees, and these differences show up later in retention.

How Enterprise Multifamily Operators Automate Move-In and Move-Out Across Yardi, RealPage, and Entrata

The fix: one move layer across every platform

The way to standardize without consolidating systems is to add a move layer that integrates with each property management system via its APIs and runs a single resident-facing move-in and move-out workflow on top of them. Yardi already supports this through its Standard Interface Partnership Program and Voyager Web Services, with a large certified partner ecosystem. RealPage and Entrata also support equivalent integration paths, as we detail in our piece on how PMS platforms like Yardi can integrate resident move-in and move-out automation.

  • The move layer connects to Yardi, RealPage, and Entrata via their APIs, so lifecycle events trigger the same workflow regardless of the underlying platform.
  • Every resident across the estate follows a single guided move-in and move-out process that covers movers, packing, storage, utilities, internet, and insurance.
  • Compliance gates and reporting are standardized, and results sync back into each system of record.

Operators are already centralizing operations to achieve this kind of consistency, with Funnel Leasing finding that 80% of third-party multifamily managers are doing so. We walk through the mechanism in our breakdown of how move-in and move-out workflows became a property management revenue engine and the onboarding mechanics in our ultimate guide to resident onboarding automation.

What it captures at portfolio scale

One move layer across a mixed estate captures the ancillary revenue that a fragmented process leaves on the table, ensures consistent compliance across every platform, and gives every resident the same experience, whether their property runs Yardi, RealPage, or Entrata. The uncaptured non-rent opportunity sits at roughly $15 per unit per month, per the Moved CEO’s RevGen leak map, and at enterprise scale the gap between platforms is exactly what standardization closes.

How Moved fits

Moved is the move-in and move-out infrastructure platform that integrates alongside each property management system through the API. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services, including movers, packing, storage, utilities, internet, and insurance verification, directly into the resident workflow, and runs one standardized experience across Yardi, RealPage, and Entrata. At the same time, each stays the system of record. Resident perks, rewards, and partnerships run on Paylode, a Moved company that Moved acquired in November 2025 to advance ancillary revenue automation, per the Moved announcement. The resident-facing experience lives inside the Moved resident experience. Moved is built on flexible commercial structures designed to align with property financial goals.

To standardize the move across your entire estate, book a walkthrough with our team or visit the Moved multifamily product page.

FAQs

Why do enterprise operators run multiple property management systems?
Acquisitions, regional preferences, and legacy deployments leave most large portfolios on a mix of Yardi, RealPage, and Entrata.

Why not consolidate to one platform?
These systems are the system of record for leasing, accounting, and operations, and consolidating them across a large portfolio is a multi-year project no operator wants to run just to standardize the move.

How does a move layer standardize across platforms?
It integrates with each property management system through its APIs. It runs one resident-facing move-in and move-out workflow on top, so the experience is the same regardless of the underlying system.

Does the property management system stay in place?
Yes. Each platform remains the system of record, and the move layer standardizes the resident experience and returns data both ways.

What does standardizing capture?
Consistent ancillary revenue, even compliance, and one resident experience across the whole estate.

The bottom line

In residential real estate, an enterprise portfolio is only as consistent as its most valuable workflow. A move layer that integrates with Yardi, RealPage, and Entrata standardizes the move-in and move-out experience across the whole estate, capturing revenue that a fragmented process leaks and ensuring consistent compliance, without the cost and risk of consolidating systems.

For the NOI picture, see our guide to increasing multifamily NOI without raising rent.

How SFR and Build-to-Rent Operators Standardize Move-In and Move-Out Across a Distributed Portfolio

Single-family rental and build-to-rent portfolios do not have a leasing office at every door. The homes are spread across markets and often across states, which means the move-in and move-out experience is defined by whatever each local team or vendor does. At 10,000+ home scale, that inconsistency is where revenue leaks and the resident experience drifts. We cover the broader operating model in our guide to ancillary revenue in multifamily.

This guide lays out why a distributed portfolio makes move-in and move-out so hard to standardize, and the resident-facing workflow that gives every home the same experience, the same revenue capture, and the same compliance, no on-site office required.

Why distribution breaks the move-in and move-out experience

In conventional multifamily, an on-site team runs the move at the property. In single-family rental and build-to-rent, there is no such team at each home. A resident moving into a house in one market gets a different experience from a resident moving into a house two states away, because the process depends on local staff, local vendors, and local habits rather than a single standard.

The result is that the move-in and move-out window, the highest-intent moment in the resident lifecycle, is run inconsistently across the book. Ancillary revenue is captured in some markets and missed in others; insurance verification happens in some homes and slips in others; and the resident experience swings from home to home for reasons unrelated to the resident.

What inconsistency costs at scale

Across a distributed portfolio, the cost of running move-in and move-out differently in every market adds up.

  • Ancillary revenue leaks wherever the local process does not surface movers, storage, utilities, internet, and insurance at the moment the resident is making a decision.
  • Renters insurance verification is uneven, and the industry baseline for correct verification already sits near 55%, per Foxen’s research, which multiplies liability exposure across thousands of scattered homes.
  • Turnover cost, already close to $3,872 per resident across multifamily per Multifamily Dive, is harder to control without a standard turn process.
  • Brand and resident experience vary home to home, which shows up later in retention.n

The fix: a resident-facing workflow that standardizes every home

The answer for a distributed portfolio is a resident-facing move-in and move-out workflow that runs identically across every home and market, because it lives with the resident rather than with a local office. Operators are already centralizing operations to reach this consistency, with Funnel Leasing finding that 80% of third-party multifamily managers are centralizing, and a standardized move workflow is what centralization needs at the resident layer.

  • Every resident, in every market, moves through the same guided move-in and move-out flow with movers, packing, storage, utilities, internet, and insurance embedded at the moment of decision.
  • Insurance verification and documentation are standardized checkpoints, so compliance is handled the same way across every home.
  • The asset management team gets a single portfolio-wide view rather than different processes in each market.

We detail the mechanism in our breakdown of how move-in and move-out workflows became a property management revenue engine and the onboarding mechanics in our ultimate guide to resident onboarding automation.

How SFR and Build-to-Rent Standardize Move-In and Move-Out

What it captures at portfolio scale

Standardized across every home, the workflow captures the ancillary revenue that a fragmented process leaves on the table, holds insurance compliance evenly across markets, and delivers one consistent resident experience. The uncaptured non-rent opportunity sits at roughly $15 per unit per month, per the Moved CEO’s RevGen leak map, and in a distributed portfolio the gap between the best and worst markets is exactly what standardization closes.
How Moved fits

Moved is the move-in and move-out infrastructure platform that gives every home the same experience without an on-site office. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services, including movers, packing, storage, utilities, internet, and insurance verification, directly into the resident workflow, and standardizes it across every market from one place. Resident perks, rewards, and partnerships run on Paylode, a Moved company that Moved acquired in November 2025 to advance ancillary revenue automation, per the Moved announcement. The property management system stays the system of record, and the resident-facing experience lives inside the Moved resident experience. Moved is built on flexible commercial structures designed to align with property financial goals.
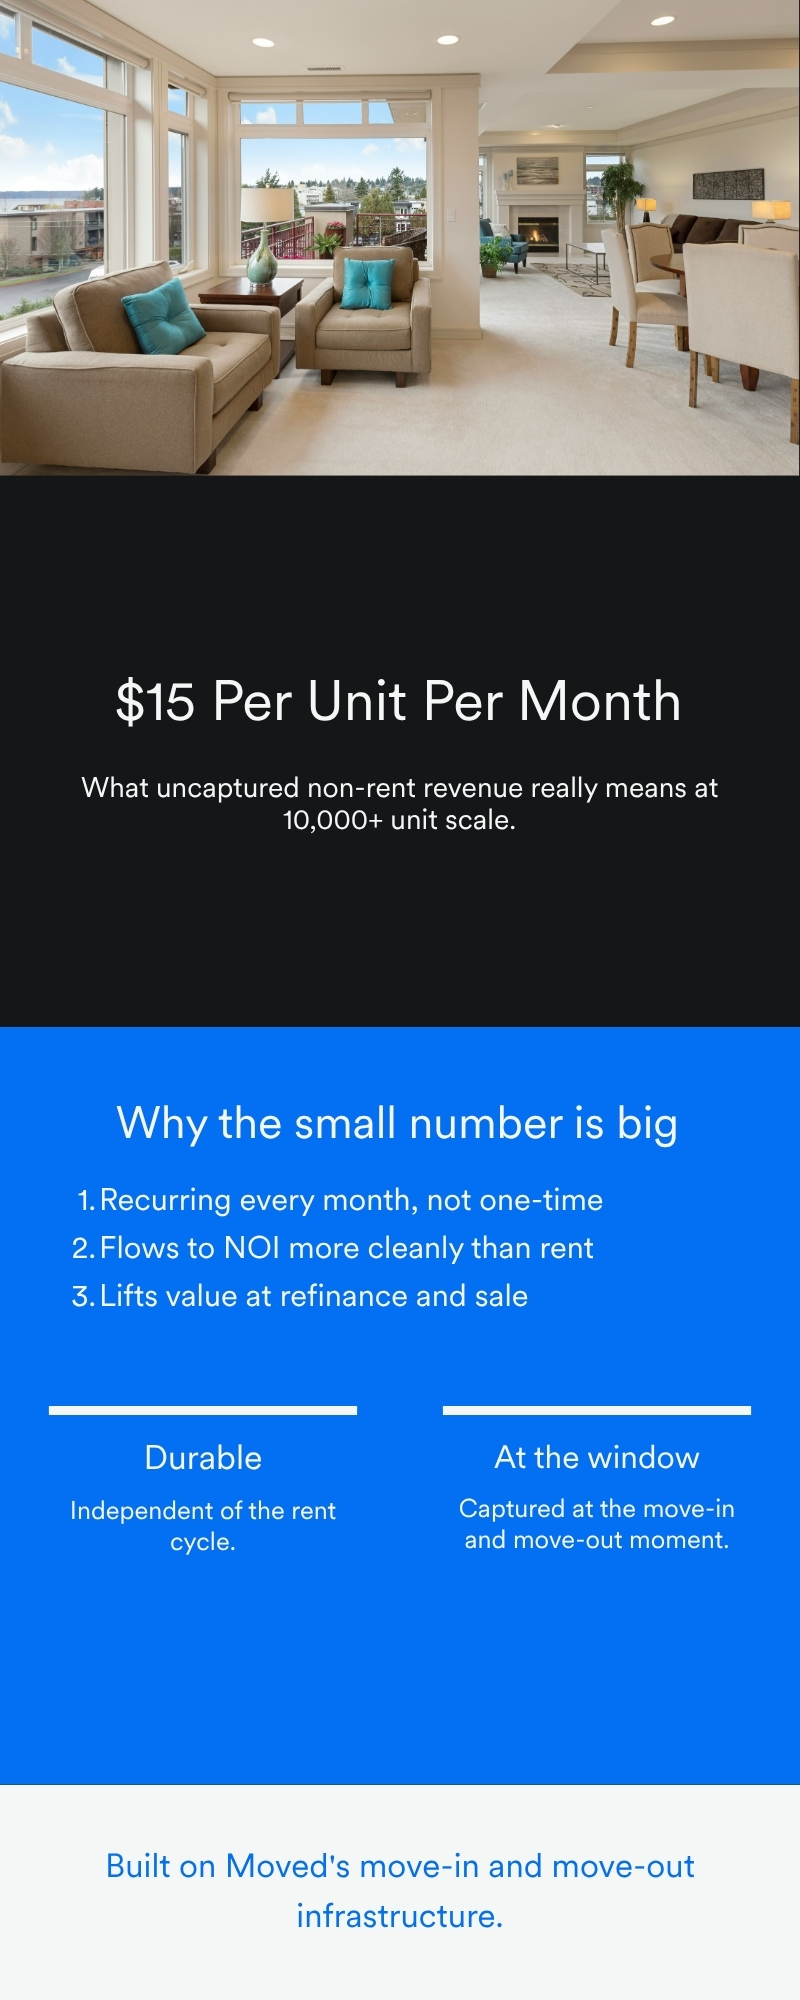
To give every home in your portfolio the same move experience, book a walkthrough with our team or visit the Moved multifamily product page.

FAQs

Why is move-in and move-out harder for SFR and build-to-rent?
Because there is no on-site team at each home, the experience depends on local staff and vendors and varies market to market.

What does that inconsistency cost?
Leaked ancillary revenue, uneven insurance verification, harder-to-control turnover costs, and a resident experience that swings home to home.

How does a resident-facing workflow fix it?
It lives with the resident rather than a local office, so every home in every market runs the same guided move-in and move-out flow with the same services and compliance gates.

Does it work without local staff?
Yes. The workflow is resident-facing and self-guided, which is exactly what a distributed portfolio needs.

Does it replace the property management system?
No. The property management system remains the system of record, and the move workflow standardizes the resident experience on top of it.

The bottom line

For single-family rental and build-to-rent operators, a growing corner of residential real estate, the move-in and move-out experience is only as consistent as the process behind it. A resident-facing workflow that runs identically across every home captures the revenue a fragmented process leaks, maintains consistent compliance, and gives every resident the same experience regardless of which market they live in.

For the NOI picture, see our guide to increasing multifamily NOI without raising rent.

How Student Housing Operators Handle Bulk Move-In and Move-Out Turn Cycles

In student housing, the move-in and move-out cycle does not spread evenly across the year. It compresses into a few weeks each summer, when almost an entire property turns at once. That concentration is where the largest revenue opportunity and the sharpest operational and compliance risks both sit for a 10,000+-bed operator. We cover the broader operating model in our guide to ancillary revenue in multifamily.

This guide lays out why the compressed turn cycle is so costly, and the standardized move-in and move-out workflow that lets student housing operators capture revenue, control risk, and run the crunch without chaos.

Why the compressed turn is the hardest window in student housing

A conventional multifamily community turns a fraction of its units in any given month. A student property turns most of its beds inside a narrow summer window, with move-outs, make-readies, and move-ins stacked on top of each other. Every resident is deciding about movers, storage, utilities, internet, and insurance at the same moment, and the on-site team is doing it hundreds of times in parallel.

That concentration magnifies everything. The revenue opportunity is dense, because the whole property is transacting at once. The cost is dense too, and turnover already runs close to $3,872 per resident across multifamily, per Multifamily Dive’s reporting on Zego’s research, with a National Apartment Association survey putting most turn costs between $1,500 and $3,500 per unit, per Multi-Housing News. Compress that into a few weeks, and the pressure on staff, timelines, and the resident experience is intense.

What breaks when the turn is run manually

Most student operators run the summer turn on spreadsheets, email, and on-site memory, at a normal volume that survives. At peak-turn volume, it does not.

  • Ancillary revenue goes uncaptured because no one has time to offer movers, storage, or insurance to every resident during the crunch.
  • Renters insurance verification slips at exactly the moment liability exposure is highest, and the industry baseline for correct verification already sits near 55%, per Foxen’s research.
  • Move-in and move-out timelines collide, so make-readies fall behind, and beds are not ready on day one.e
  • The resident experience varies bed to bed depending on which staff member handled it.

The fix: one standardized workflow that scales with the spike

The way through the crunch is a standardized move-in and move-out workflow that runs the same way for every bed and carries its own capacity when volume spikes, because it does not depend on staff remembering steps.

  • Every resident moves through the same guided move-in and move-out flow, with movers, packing, storage, utilities, internet, and insurance embedded at the moment of decision.
  • Insurance verification and documentation are gates in the workflow, not tasks someone has to chase during the busiest week of the year.
  • The asset management team sees the status across the whole portfolio in real time, so make-readies and move-ins can be sequenced rather than colliding.

We detail the mechanism in our breakdown of how move-in and move-out workflows became a property management revenue engine and the onboarding mechanics in our ultimate guide to resident onboarding automation.

Infographic - How Student Housing Operators Handle Bulk Move-In and Move-Out Turn Cycles

What it captures at portfolio scale

Run consistently across a large student portfolio, the standardized workflow captures the dense ancillary revenue the summer turn concentrates, holds insurance compliance through the peak, and takes pressure off the on-site team. The uncaptured non-rent opportunity sits at roughly $15 per unit per month across the book, per the Moved CEO’s RevGen leak map, and in student housing much of it concentrates in the turn.

How Moved fits

Moved is the move-in and move-out infrastructure platform built to run at peak-turn volume. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services, including movers, packing, storage, utilities, internet, and insurance verification, directly into the resident workflow, and gives the asset management team portfolio-wide visibility through the turn. Resident perks, rewards, and partnerships run on Paylode, a Moved company that Moved acquired in November 2025 to advance ancillary revenue automation, per the Moved announcement. The property management system stays the system of record, and the resident-facing experience lives inside the Moved resident experience. Moved is built on flexible commercial structures designed to align with property financial goals.
To run your summer turn on a standardized workflow, book a walkthrough with our team or visit the Moved multifamily product page.

FAQs

Why is the student housing turn cycle so hard?
Because most beds turn inside a narrow summer window, stacking move-outs, make-readies, and move-ins on top of each other and concentrating both revenue and risk.

What gets lost when the turn is run manually?
Ancillary revenue goes uncaptured, insurance verification slips, timelines collide, and the resident experience varies bed to bed.

How does a standardized workflow help?
It runs the same guided move-in and move-out flow for every bed, embeds services and insurance gates, and gives real-time portfolio visibility so the spike is sequenced rather than chaotic.

Does it require replacing the property management system?
No. The property management system remains the system of record, and the move workflow adds resident experience and verification on top.

Where is the revenue in the turn?
In the dense ancillary decisions, movers, storage, utilities, internet, and insurance, that every resident makes at once during the move-in and move-out window.

The bottom line

In student housing, a corner of residential real estate defined by the summer turn, the compressed move-in and move-out window is the whole game. A standardized workflow that carries its own capacity through the spike captures the dense revenue, holds compliance, and lets the on-site team run the busiest weeks of the year without breaking.

For the NOI picture, see our guide to increasing multifamily NOI without raising rent.

What $15 Per Unit Per Month in Non-Rent Revenue Actually Means at 10,000+ Unit Scale

The Moved CEO’s RevGen work puts one number on the table for a 10,000+ unit operator: roughly $15 per unit per month in typically uncaptured non-rent revenue, most of it concentrated in the move-in and move-out window. The figure is small per unit and easy to wave off, and that is exactly why it is misread. This guide explains what $15 per unit per month actually means once you understand how that revenue behaves. The figure comes from the Moved CEO’s RevGen leak map.

For the broader model, see our guide to ancillary revenue in multifamily.

It is recurring, not one-time.

The first thing $15 per unit per month means is that it repeats. This is not a one-time fee at move-in. It is a monthly figure that recurs across the portfolio, month after month, and renews as residents cycle through the move-in and move-out window. Recurring revenue is worth far more than the same amount collected once, because it compounds across every unit and every turn.

It flows to NOI cleanly.y

The second thing it means is quality. Partnership-based non-rent revenue carries minimal incremental operating cost. Hence, a dollar of it lands closer to a dollar of net operating income than a dollar of rent does, which arrives carrying its share of operating expense. That is why asset managers treat well-captured non-rent revenue as some of the highest-quality income on the statement, not as a rounding line.

It shows up in value.

The third thing it means is the durability of value. Multifamily assets are valued on net operating income, so recurring income that flows cleanly to NOI also lifts the asset’s value at refinance and at sale. Revenue captured consistently across the book strengthens the number that lenders and buyers underwrite, which is why non-rent revenue has moved from a footnote to a line the capital markets pay attention to.

It does not depend on the rent cycle.

The fourth thing it means is independence from the market. Rent growth rises and falls with the cycle. The $15 per unit per month is captured from resident spend that is already happening during the move-in and move-out window, so it does not require a rent tailwind, a renovation, or a concession war to produce. It grows income without raising rent, which is exactly the pressure most operators are under. We make that case in our guide to increasing multifamily NOI without raising rent.

The Compliance-First Move-In and Move-Out Workflow

Why does it concentrate on the move-in and move-out window?

The reason the figure sits where it does is intentional. The move-in and move-out window is when residents are actively deciding on movers, packing, storage, utilities, internet, and insurance, making it the highest-intent, highest-margin moment in the resident lifecycle. Capture the window well, and the per-unit figure is realized. Miss it, and the same revenue walks out the door to a third party. We walk through the mechanism in our breakdown of how move-in and move-out workflows became a property management revenue engine and the onboarding mechanics in our ultimate guide to resident onboarding automation.

How Moved fits

Moved is the move-in and move-out infrastructure platform that captures the per-unit figure and returns it as measurable revenue. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services, including movers, packing, storage, utilities, internet, and insurance verification, directly into the resident workflow, then reports the result to the asset management team by property, stream, attach rate, and margin. Resident perks, rewards, and partnerships run on Paylode, a Moved company that Moved acquired in November 2025 to advance ancillary revenue automation, per the Moved announcement. The resident-facing experience lives inside the Moved resident experience. Moved is built on flexible commercial structures designed to align with property financial goals.
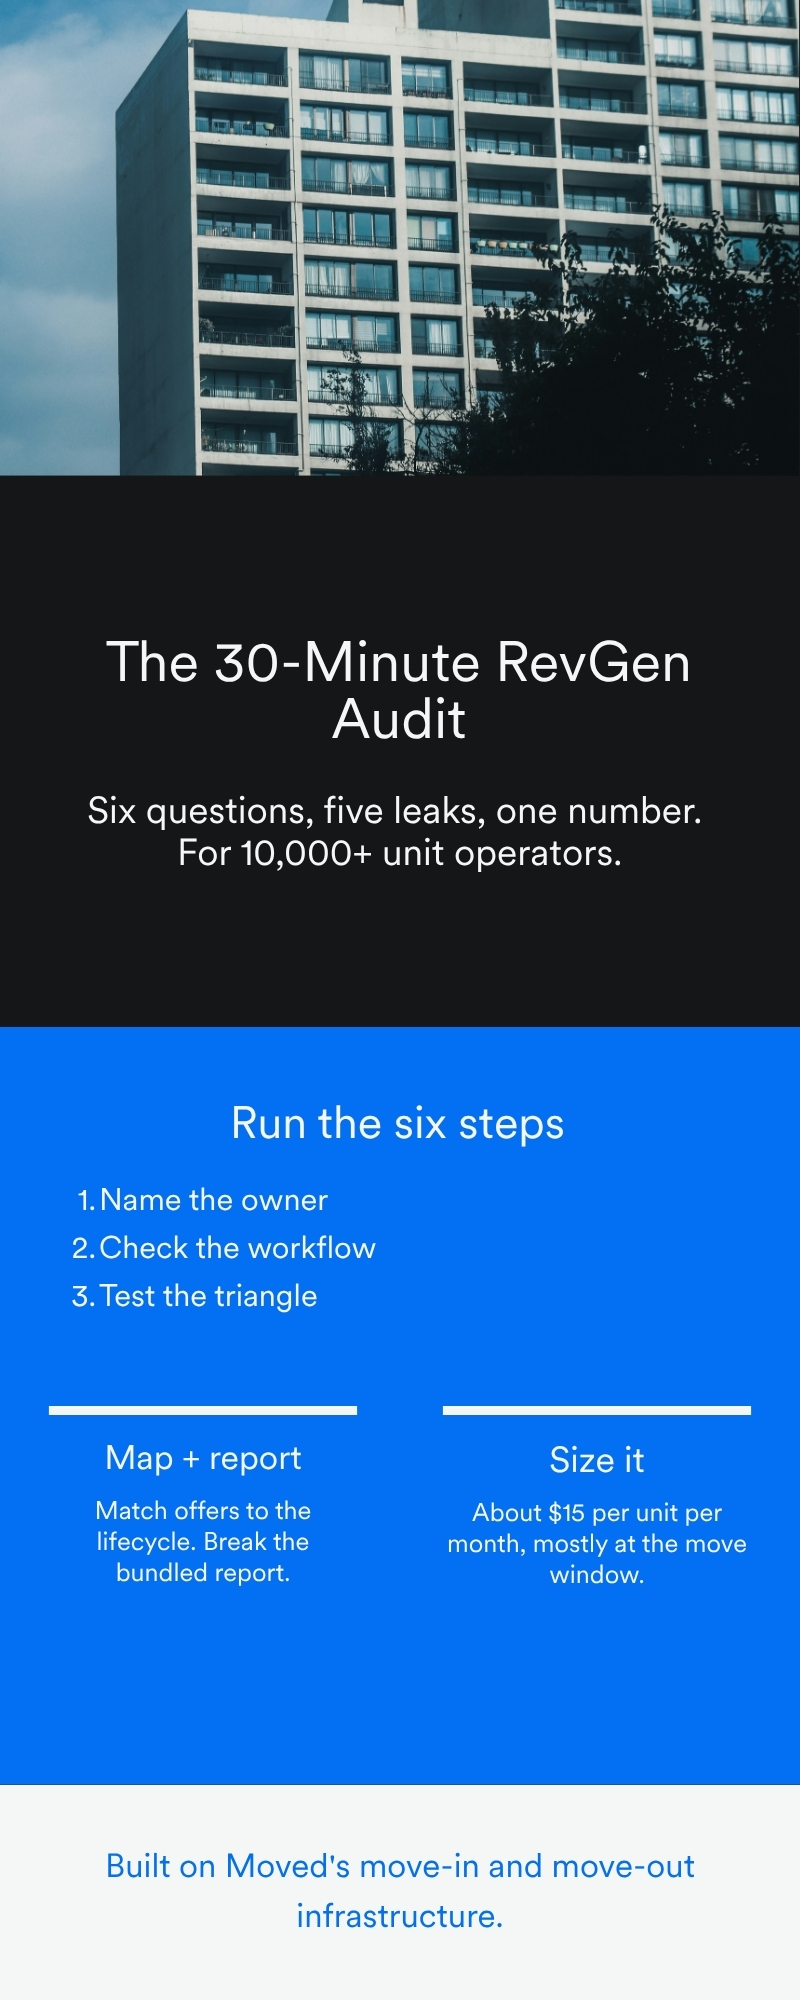
To see what the per-unit figure looks like across your own portfolio, book a walkthrough with our team or visit the Moved multifamily product page.

FAQs

What is the $ 15-per-unit-per-month figure?
It is the roughly $15 per unit per month in typically uncaptured non-rent revenue that the Moved CEO’s RevGen leak map identifies, most of it concentrated in the move-in and move-out window.

Why does a small per-unit figure matter?
Because it recurs monthly across the portfolio, flows cleanly to NOI, and lifts asset value, making it worth far more than the per-unit number suggests.

Why is it higher quality than rent?
Partnership-based non-rent revenue carries minimal incremental operating cost, so more of each dollar reaches net operating income.

Does it depend on rent growth?
No. It is captured from resident spend that already occurs during the move-in and move-out window, independent of the rent cycle.

Where is it captured?
At the move-in and move-out window, the highest-intent moment in the resident lifecycle.

The bottom line

In residential real estate, $15 per unit per month is not a small number; it is a recurring, high-quality, cycle-independent stream that flows to NOI and shows up in value. Understood correctly, it reframes the move-in and move-out window from an operational task to one of the cleanest sources of NOI for a 10,000+ unit operator.

For the resident view, browse the Moved resident experience.
The 30-Minute RevGen Audit: A CFO’s Checklist for 10,000+ Unit Multifamily Portfolios

A CFO does not need a six-month study to know whether non-rent revenue is leaking. Thirty minutes and six questions are enough. This audit walks a 10,000+ unit operator through the five RevGen leaks and sizes the opportunity at the end, so the move-in and move-out window is no longer a blind spot on the operating statement. The framework is based on the Moved CEO’s RevGen leak map.

Run the six steps below in order. Each one maps to a leak, and each has a clear pass or fail. For the broader model, see our guide to ancillary revenue in multifamily.

Step 1: Name the owner

Ask who the single named person is whose compensation is tied to the non-rent revenue. If the answer is a committee or a shared responsibility, the ownership leak is open. A clear owner with a target, a dashboard, and the authority to act is a pass.

Step 2: Check the workflow

Ask whether the non-rent offer depends on a leasing agent remembering to make it. If revenue relies on memory during the move-in and move-out rush, the workflow leak is open. An offer embedded in the workflow and default-visible to every resident is a pass.

Step 3: Test the triangle

Take your largest ancillary program and ask whether the resident, the operator, and the partner all win. If anyone is losing, the program is on borrowed time, and the incentive leak is open—a program where all three win is a pass.

Step 4: Map the lifecycle

Ask whether offers are timed to the resident’s intent or broadcast all at once. If the same offer goes out regardless of the moment, the lifecycle leak is open. Offers matched to the application, the move-in and move-out window, living, and renewal are a pass.

Step 5: Break the report

Ask whether non-rent revenue is reported as one bundled “other income” line or as a category-level scorecard. If it is one number, the reporting leak is open. Revenue per unit by category, attach rate, margin by stream, and resident satisfaction impact are a pass.

Step 6: Size the opportunity

Finish by sizing the leaks. The Moved CEO’s RevGen leak map sizes the typically uncaptured non-rent opportunity at roughly $15 per unit per month, most of it concentrated in the move-in and move-out window. Multiply that by the units in the portfolio to see why the audit is worth the thirty minutes. We detail the mechanism in our breakdown of how move-in and move-out workflows became a property management revenue engine and the onboarding mechanics in our ultimate guide to resident onboarding automation.

Reading the results

Any step that fails is a specific, fixable leak with a named owner, a workflow change, a program redesign, a timing fix, or a reporting change behind it. The audit turns a vague sense that non-rent revenue could be improved into a prioritized list of moves, all of which point back to the move-in and move-out window, where the largest opportunity lies.

30-minute-revgen-audit-cfo-checklist

How Moved fits

Moved is the move-in and move-out infrastructure platform that closes the leaks that the audit surfaces. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services, including moving, packing, storage, utilities, internet, and insurance verification, directly into the resident workflow, and returns category-level data to the asset management team. Resident perks, rewards, and partnerships run on Paylode, a Moved company that Moved acquired in November 2025 to advance ancillary revenue automation, per the Moved announcement. The resident-facing experience lives inside the Moved resident experience. Moved is built on flexible commercial structures designed to align with property financial goals.
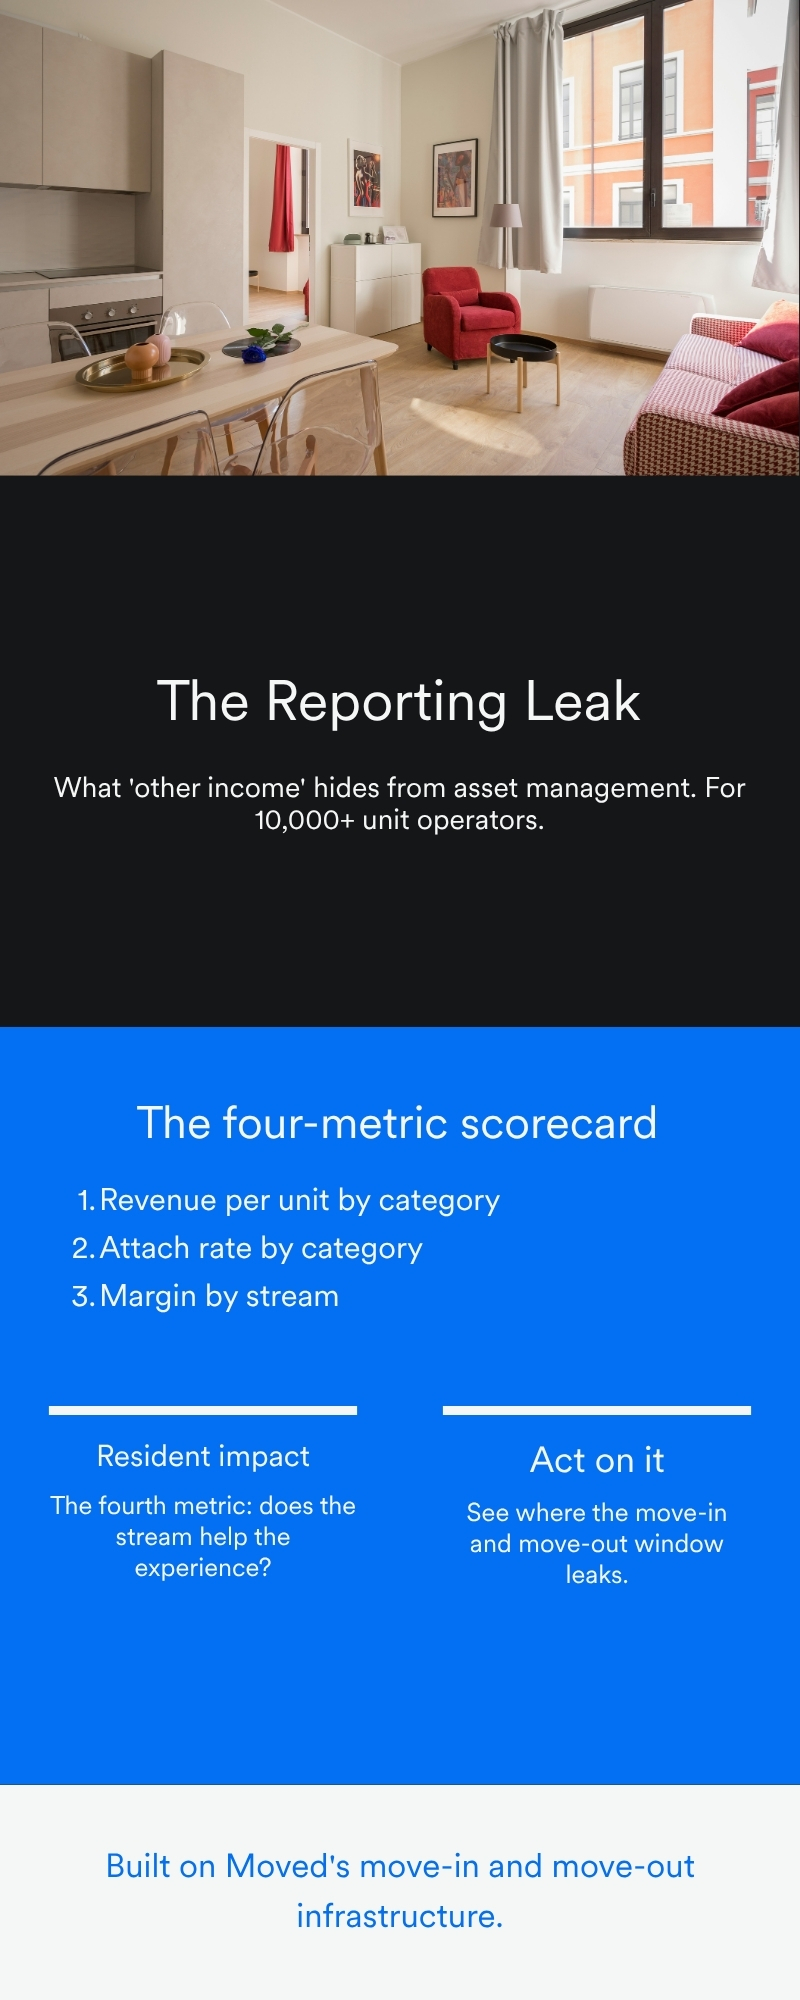
To run the audit against your own portfolio with our team, book a walkthrough or visit the Moved multifamily product page.

FAQs

What is the 30-Minute RevGen Audit? A six-step checklist that walks a 10,000+ unit operator through the five RevGen leaks and sizes the opportunity, fast enough to run in a single sitting.

What are the six steps? Name the owner, check the workflow, test the triangle, map the lifecycle, break the report, and size the opportunity.

What sizing figure does the audit use? Roughly $15 per unit per month in typically uncaptured non-rent revenue, from the Moved CEO’s RevGen leak map, most of it in the move-in and move-out window.

Who should run it? The CFO or asset management leader, with operations able to answer the workflow and lifecycle questions.

What do I do with a failed step? Each failure maps to a specific fix: an owner, an embedded workflow, a program redesign, a timing change, or a category-level report.

The bottom line

In residential real estate, non-rent revenue is easy to audit and expensive to ignore. Six questions surface the five leaks; the sizing step shows what they are worth; and every answer points back to the move-in and move-out window as the place to start.

For the NOI picture, see our guide to increasing multifamily NOI without raising rent.

The Reporting Leak: What “Other Income” Hides That Your Asset Management Team Needs to See

At a 10,000+ unit operator, non-rent revenue from the move-in and move-out window is real money, and most asset management teams see it as a single bundled number called “other income.” That bundling is the fifth leak in the RevGen system: the reporting leak. When every stream collapses into one line, the team loses the ability to manage, and revenue you cannot see is revenue you cannot compound. The framing comes from the Moved CEO’s RevGen leak map.

This guide covers what the bundled line hides, the four-metric scorecard that replaces it, and why the move-in and move-out window is where the reporting leak costs the most. For the broader model, see our guide to ancillary revenue in multifamily.

What one bundled line hides

“Other income” treats a portfolio of distinct revenue streams- parking, pet rent, storage, utilities, insurance, and the partnership income that concentrates in the move-in and move-out window- as one undifferentiated bucket. A single number cannot tell the asset management team which streams are working, which are flat, where attach rates are strong, or where margin is thin. It reports a total while hiding every input that could improve it.

The result is that non-rent revenue drifts inside the line. A stream can fall for two quarters, and the bundled number barely moves, so nobody acts. The reporting leak is not a missing dollar; it is a missing signal.

The four-metric scorecard

Closing the reporting leak means replacing the bundled line with a category-level scorecard the asset management team can act on.

  • Revenue per unit by category. Break the total into its streams so each can be tracked and targeted individually.
  • Attach rate by category. The share of residents who take each service is the truest measure of whether the move-in and move-out workflow is capturing the opportunity.
  • Margin by stream. Not all revenue is equal, and partnership-based streams flow to NOI far more cleanly than others.
  • Resident satisfaction impact. Whether a stream strengthens or strains the resident experience, revenue that erodes retention is not a win.

With those four visible, the team can see exactly where the move-in and move-out window is capturing revenue and where it is leaking, and can act on the specific stream rather than guessing at a total.

Why does the move-in and move-out window cost the most

The bundled line hides the highest revenue of all, because the move-in and move-out window is where the highest-intent, highest-margin non-rent revenue is concentrated. The Moved CEO’s RevGen leak map sizes the typically uncaptured non-rent opportunity at roughly $15 per unit per month, most of it in that window. When that revenue sits in “other income,” the team cannot even see whether it is being captured, which is why the reporting leak must be closed before the others can be managed. We walk through the mechanism in our breakdown of how move-in and move-out workflows became a property management revenue engine and the onboarding mechanics in our ultimate guide to resident onboarding automation.

The Compliance-First Move-In and Move-Out Workflow

How Moved fits

Moved is the move-in and move-out infrastructure platform that turns the bundled line into a scorecard. Traditional tools focus on task tracking and administrative coordination. Moved embeds revenue-generating services, including movers, packing, storage, utilities, internet, and insurance verification, directly into the resident workflow, then returns the results to the asset management team as category-level data by property, stream, attach rate, and margin. Resident perks, rewards, and partnerships run on Paylode, a Moved company that Moved acquired in November 2025 to advance ancillary revenue automation, per the Moved announcement. The resident-facing experience lives inside the Moved resident experience. Moved is built on flexible commercial structures designed to align with property financial goals.

To replace your bundled line with a category-level scorecard, book a walkthrough with our team or visit the Moved multifamily product page.

FAQs

What is the reporting leak in RevGen? It is the loss of signal that happens when non-rent revenue is bundled into a single “other income” line. The team can see a total, but none of the inputs needed to manage it.

Why is “other income” the wrong way to manage non-rent revenue? Because it collapses distinct streams into one number, hiding category performance, attach rate, margin, and resident impact.

What four metrics replace the bundled line? Revenue per unit by category, attach rate by category, margin by stream, and resident satisfaction impact.

Why does the move-in and move-out window matter most here? Because it holds the highest-intent, highest-margin non-rent revenue, and bundling hides whether that revenue is captured at all.

Who uses the scorecard? The asset management team, with on-site teams executing the workflow and the platform maintaining consistent data across the portfolio.

The bottom line

In residential real estate, you cannot compound what you cannot see. Replacing the bundled “other income” line with a four-metric scorecard- revenue per unit by category, attach rate, margin, and resident satisfaction impact- gives the asset management team the signal to manage non-rent revenue, starting with the move-in and move-out window where it matters most.

For the NOI picture, see our guide to increasing multifamily NOI without raising rent.